

Robin research covers small and medium-sized companies with an attractive risk/reward profile mainly in Europe and North America.
Disclaimer: this is neither a buy and sell recommendation nor private advice. Investing in companies carries a risk of permanent loss of capital. Before investing in a company do your own research
1. Key inputs
Monopolistic niche micro cap.
Disastrous 2025 but good prospects for 2026.
Possibility of multiplying the investment by 2 or 3 times.
2. Company overview
CTT Systems is the market leader in developing and manufacturing active humidity control systems for the global aviation industry. The company solves the "moisture paradox" by addressing both unhealthily dry cabin air and excessive fuselage condensation.
CTT Systems AB (publ) was incorporated in 1991 and is based in Nyköping, Sweden.
3. Product and revenue mix
CTT Systems specializes in active humidity control for the global aviation industry, offering two primary product groups that solve the “moisture paradox” in aircraft.
• Humidifiers (Humidifier Onboard): These systems elevate humidity in the cockpit, crew rest areas, and premium passenger cabins from unhealthily dry levels (near 0%) to comfortable, ground-like levels (20–25% RH). This enhances well-being, improves sleep quality, and reduces the effects of jet lag and fatigue.
• Anti-Condensation Systems (Dehumidifiers): These systems actively remove trapped moisture and ice from the aircraft fuselage. By eliminating up to 300 kg of excess water weight, they improve fuel economy and reduce CO2 emissions by approximately 65–100 tonnes per aircraft annually.
With a highly diversified global customer base of more than 60 major airlines, CTT is the sole supplier for the industry’s most advanced long-haul platforms: the Boeing 787, Airbus A350, and the upcoming Boeing 777X.
Looking at its historical sales mix. Between 2020 and 2025, the company maintained a balanced and highly profitable revenue distribution:
• Aftermarket (66.5%): The primary driver of recurring high-margin revenue through consumables (pads) and repairs.
• OEM (18.3%): Direct factory installations, set to regain weight in the mix as production accelerates.
• Private Jets (8.8%): A stable VIP segment now reaching new heights through partnerships with Airbus Corporate Jets (ACJ) and Boeing Business Jets (BBJ).
• Retrofit & Non-Core (6.4%): Highlighted by the recent record-breaking order from Jet2.com to retrofit 146 A321 aircraft.
The geographical distribution of CTT’s revenue potential, primarily measured by the location of its installed base of humidifiers, reveals a strong concentration in high-growth aviation corridors:
• Asia (48%): By far the company’s largest market, reflecting the region’s massive investment in modern long-haul fleets.
• Europe (21%): A mature and stable market with a high demand for both commercial cabin comfort and private jet solutions.
• North America (18%): A key region driven by major global carriers and CTT’s close relationship with Boeing.
• Rest of the World: The remaining revenue base is spread across Africa (5%), South America (4%), and Australia (3%), completing CTT’s truly global reach.
While the company’s direct financial reporting often highlights Denmark (49%) and the USA (17%) as primary revenue sources due to the location of its main distributors (like Satair) and manufacturers (Boeing), the actual end-users and the service demand are distributed according to the global flying patterns mentioned above.
4. Business and growth model 2026 - 2027
While 2025 was impacted by transitory inventory adjustments at the distributor level and currency headwinds, the outlook for 2026 and 2027 is exceptionally strong:
1. OEM Production Ramp-Up: Both Boeing and Airbus are targeting a doubling of production rates by 2026 compared to pandemic lows. Boeing aims to reach 10 units per month for the 787 by 2026, while Airbus targets 12 A350 units per month by 2028.
2. Doubling Shipset Value: Crucially, CTT’s average product value per A350 has more than doubled for new aircraft batches. Airlines are increasingly selecting humidifiers not just for the cockpit, but for entire premium passenger cabins.
3. The 777X Entry: The entry into service of the Boeing 777X, now targeted for 2026, will add a completely new revenue stream for which CTT is the sole provider.
4. Private Jet Expansion: Boeing Business Jets (BBJ) recently followed Airbus Corporate Jets (ACJ) in making cabin humidification a “baseline configuration” (standard) across its portfolio, a move that is expected to force other large business jet OEMs to follow suit.
Following a period of disciplined cost control and the stabilization of the aftermarket, CTT management anticipates that volume growth will gradually drive EBIT margins back toward 25% or higher during 2026.
5. Total adressable market
While the sources do not provide a single combined TAM figure they detail the market potential for its core business areas:
1. Commercial Aircraft Retrofit Market
• Humidification: The total market potential for retrofitting humidifiers into the premium cabins of existing widebody fleets exceeds SEK 1 billion. This is based on a target market of approximately 1,500 aircraft, including roughly 1,200 Boeing 787s and 300 Airbus A350s .
• Anti-Condensation: CTT is targeting a retrofit market for narrowbody aircraft (primarily in Northern Europe) with an estimated potential of 500 aircraft. For context, a single order for 146 such systems was valued at approximately SEK 120 million at list price .
2. Private Jet and Business Jet Market
• Large-Cabin Business Jets: CTT identifies an annual “first sales” (OEM) market potential of USD 25 million to USD 30 million (approximately SEK 250 million to SEK 300 million) for humidifiers in this sector .
• VIP Aircraft Kits: The partnership with Airbus Corporate Jets (ACJ) for small VIP aircraft (ACJ320 family) has an estimated annual revenue potential of SEK 10 million to SEK 15 million.
3. OEM (Factory Installation) Growth Drivers
The addressable OEM market is directly linked to the production ramp-ups scheduled for 2026:
• Boeing 787: Boeing aims to reach a production rate of 10 aircraft per month in 2026 (up from approximately 5 in 2024) .
• Airbus A350: Airbus targets 10 units per month in 2026, increasing to 12 by 2028.
• Boeing 777X: The entry into service, targeted for 2026, will open a new, high-value revenue stream where CTT is the sole humidifier supplier .
• Increased Value per Aircraft: The addressable value per plane is expected to more than double for A350 batches starting production in 2025/2026 as airlines increasingly select humidifiers for entire premium passenger cabins rather than just the cockpit .
4. Recurring Aftermarket Potential
The recurring market for consumables (humidity pads) and repairs tracks the “installed base” of systems in service. If Airbus and Boeing meet their production targets, CTT expects the installed base of humidifiers to grow by more than 20% per year, which will significantly expand the addressable aftermarket revenue starting in 2026.
6. Risks
CTT Systems is a business defined by volatility, lack of control, and extreme dependencies.
1. The Currency Trap: A Bet on the Dollar, Not the Business
CTT Systems operates under an unusually one-sided currency exposure, with virtually all sales conducted in USD while its cost base remains largely in SEK. This makes the company’s profitability a passive slave to the USD/SEK exchange rate. In 2020 alone, management admitted that a 10% lower average dollar rate would have slashed the operating profit (EBIT) by a staggering 41%. More recently, “currency headwinds” in 2025 significantly eroded both sales and earnings as the dollar drifted lower.
2. The Distributor “Hostage” Risk
The Aftermarket segment, which typically provides the company’s highest margins, is dangerously unpredictable. CTT is effectively at the mercy of its distributors, such as Satair and Boeing, and has little visibility into their ordering patterns. This was starkly evident in Q1 2025, when the EBIT margin plummeted to a shocking 7% because distributors decided to de-stock their well-filled inventories. This “rippling effect” means CTT’s revenue can collapse even if underlying airline demand remains stable.
3. OEM Dependency and Platform Concentration
CTT’s growth is entirely dependent on the production rates of a tiny number of aircraft platforms: the Boeing 787 and Airbus A350. Any delay or supply chain hiccup at these giants instantly paralyzes CTT’s OEM shipments.
4. The “Non-Essential” Vulnerability
A fundamental risk that the “wellness” narrative masks is that CTT’s products are not flight-critical. Humidifiers are comfort options that airlines can simply switch off during recessions to save on fuel and maintenance. Historically, the sale of anti-condensation systems has been repeatedly hindered when airlines abruptly ban investments in non-essential products during downturns.
5. Emerging Competition and Geopolitical Tail Risks
The company’s previous near-monopoly is under threat from FAA-approved third-party manufacturers (PMA) producing cheaper copies of CTT’s high-margin consumables.
CTT Systems is a “high-leverage” play on a very specific set of circumstances: a strong US dollar, aggressive widebody production ramp-ups, and a lack of competitive alternatives. If any of these pillars fail the company’s financials deteriorate rapidly. The recent decision to omit the extraordinary dividend and the extreme volatility of quarterly results should serve as a warning that this is not a stable aerospace play, but a niche operator whose destiny is controlled almost entirely by external forces.
7. Management
The largest shareholder is Tomas Torlöf (Chairman of the Board) 14% of the shares through Trulscom Förv. The rest of the management team holds only a few shares.
The dividend policy aims to distribute at least 70% of net profit annually, provided the equity ratio (solidity) remains above 40%.
For fiscal year 2024, an ordinary dividend of SEK 5.35 per share was proposed, but this year it has fallen sharply to SEK 2.40.
8. Investment thesis
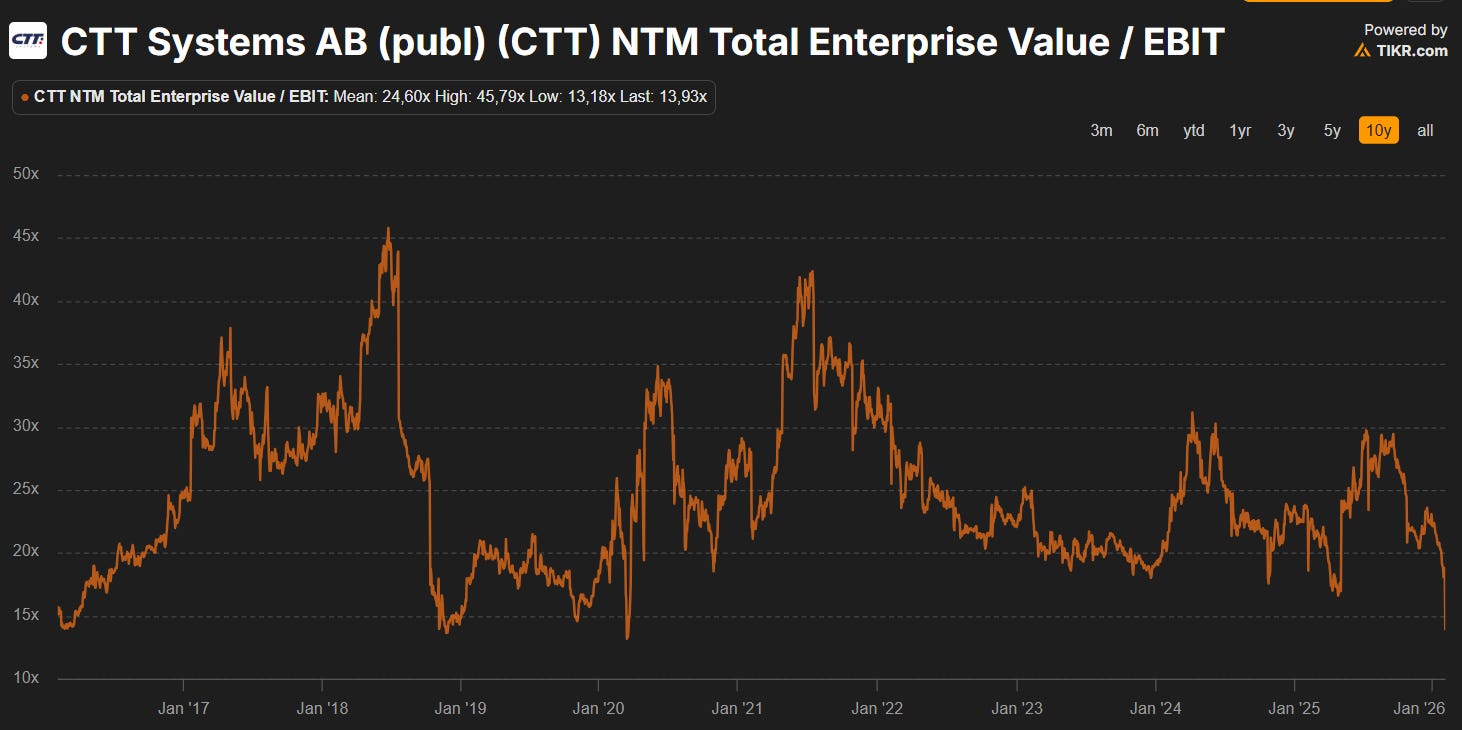
Although I don’t like the company at all because it has many red flags, I admit that the situation has become interesting.
On paper, 2025 was a “weak” year. Net sales decreased by 12% (5% in comparable currencies) to MSEK 264, and the EBIT margin dropped to 18%. However two primary external factors “masked” the underlying growth in 2025:
• The Currency “Wildcard”: A significantly weaker USD/SEK exchange rate acted as a major drag, explaining approximately MSEK 20 of the total sales decrease and impacting EBIT by MSEK 32.
• The Distributor “Rippling Effect”: After two strong years of inventory buildup, distributors aggressively destocked in 2025. Consequently, CTT’s sales to distributors were far below actual airline demand. If distributors had simply purchased what they sold to airlines, CTT’s revenues would have been MSEK 32 higher.
As we move into 2026, the temporary headwinds of 2025 are expected to dissipate, replaced by three powerful growth engines: 1. The OEM Production “Sharp Increase”, 2. Aftermarket Normalization and 3. Larger “Population” and the inventory adjustments that plagued 2025 are ending.
In the presentation of results on February 6 (when the share price ended up plummeting), management is positive about 2026, and I quote:
OEM deliveries growing – Strong outlook 2026/2027.
Private jet establishing higher net sales base-line – but quarterly variations – slow start 1H26.
Aftermarket sales higher than 2025.
EBIT margin gradual recovery in 2026 (at current FX), driven by volumes.
As sales visibility is completely unpredictable, I have taken the forecasts of the only analyst who follows the company (paid by the company itself) and created a downside scenario with EBIT at 25% and sales at -5% according to forecasts.
In the worst-case scenario, EPS for 2026 would be around SEK 3, and the base scenario would be around SEK 6, while the best-case scenario would be SEK 8. By 2027, if everything continues as planned, it could still see strong growth.
In my opinion, it’s a risky bet and it’s difficult to be convinced (at least for me), but perhaps someone more knowledgeable in this area could use this idea. However, the share price could skyrocket, multiplying by 2 or 3 by 2027. We’ll have to monitor it quarter by quarter.
See you soon, warm regards to all!